Opening a digital banking services outlet can help a local shop serve more customers by offering convenient, assisted services alongside its regular products. If you are a retailer, entrepreneur or aspiring banking service agent in India, it is worth understanding how this business works, what services may be available and what to check before choosing a service provider.
This guide explains the key steps to start a digital banking services business, from understanding service options to preparing your shop and evaluating a retailer network such as FCSPAY.
What is a digital banking services business?
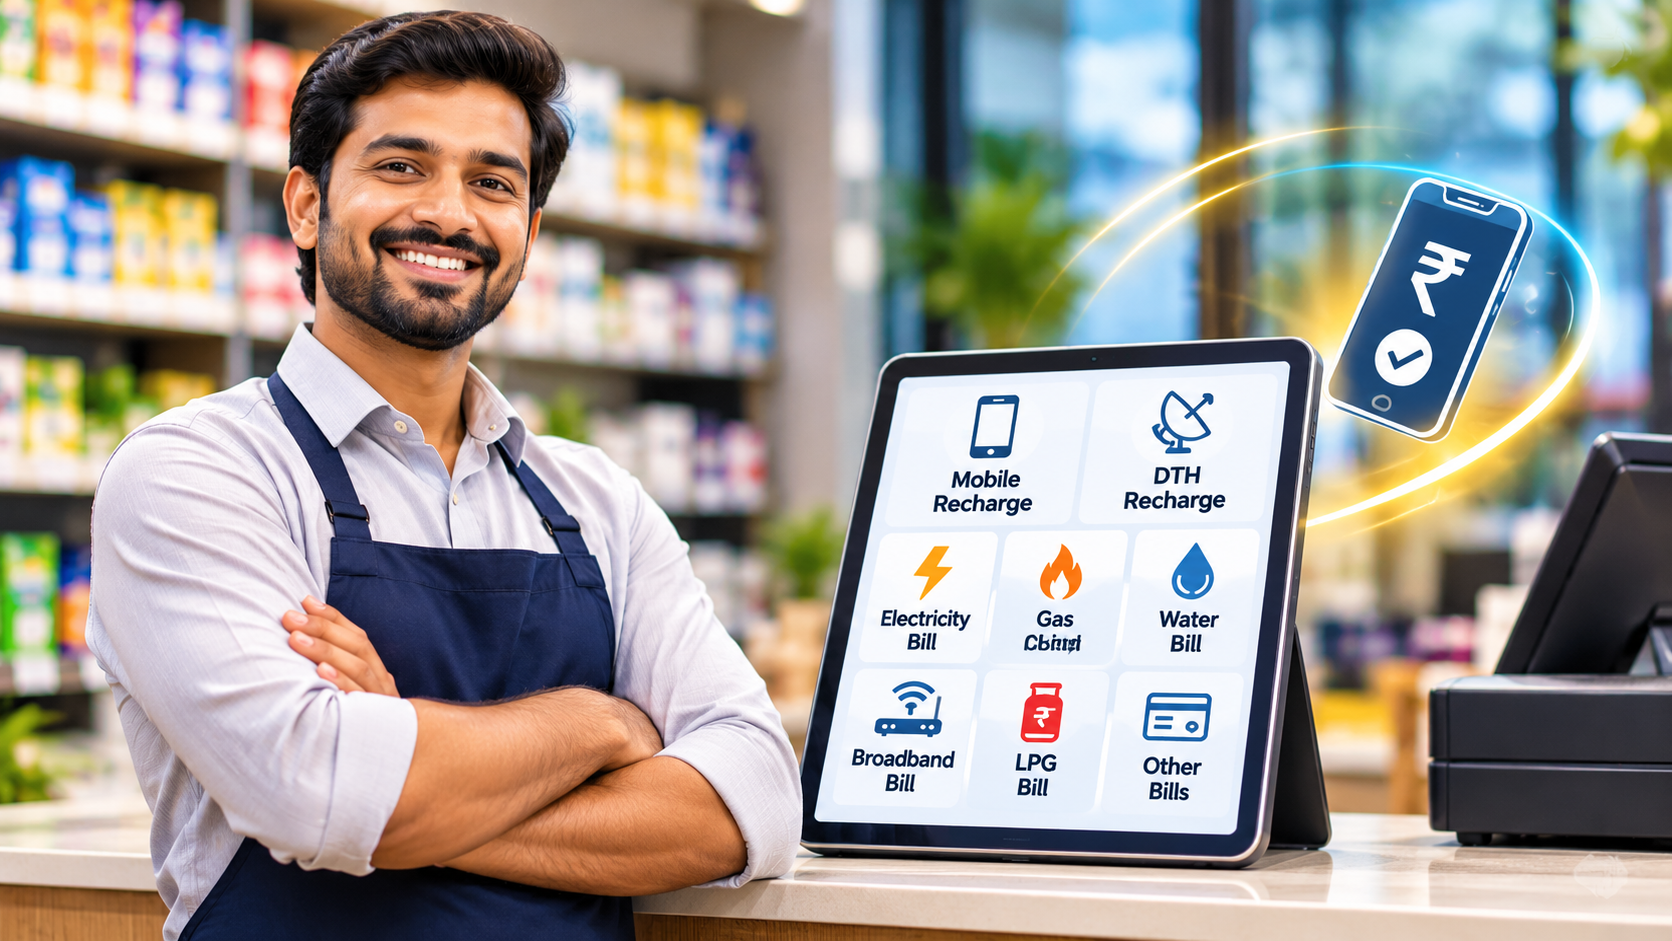
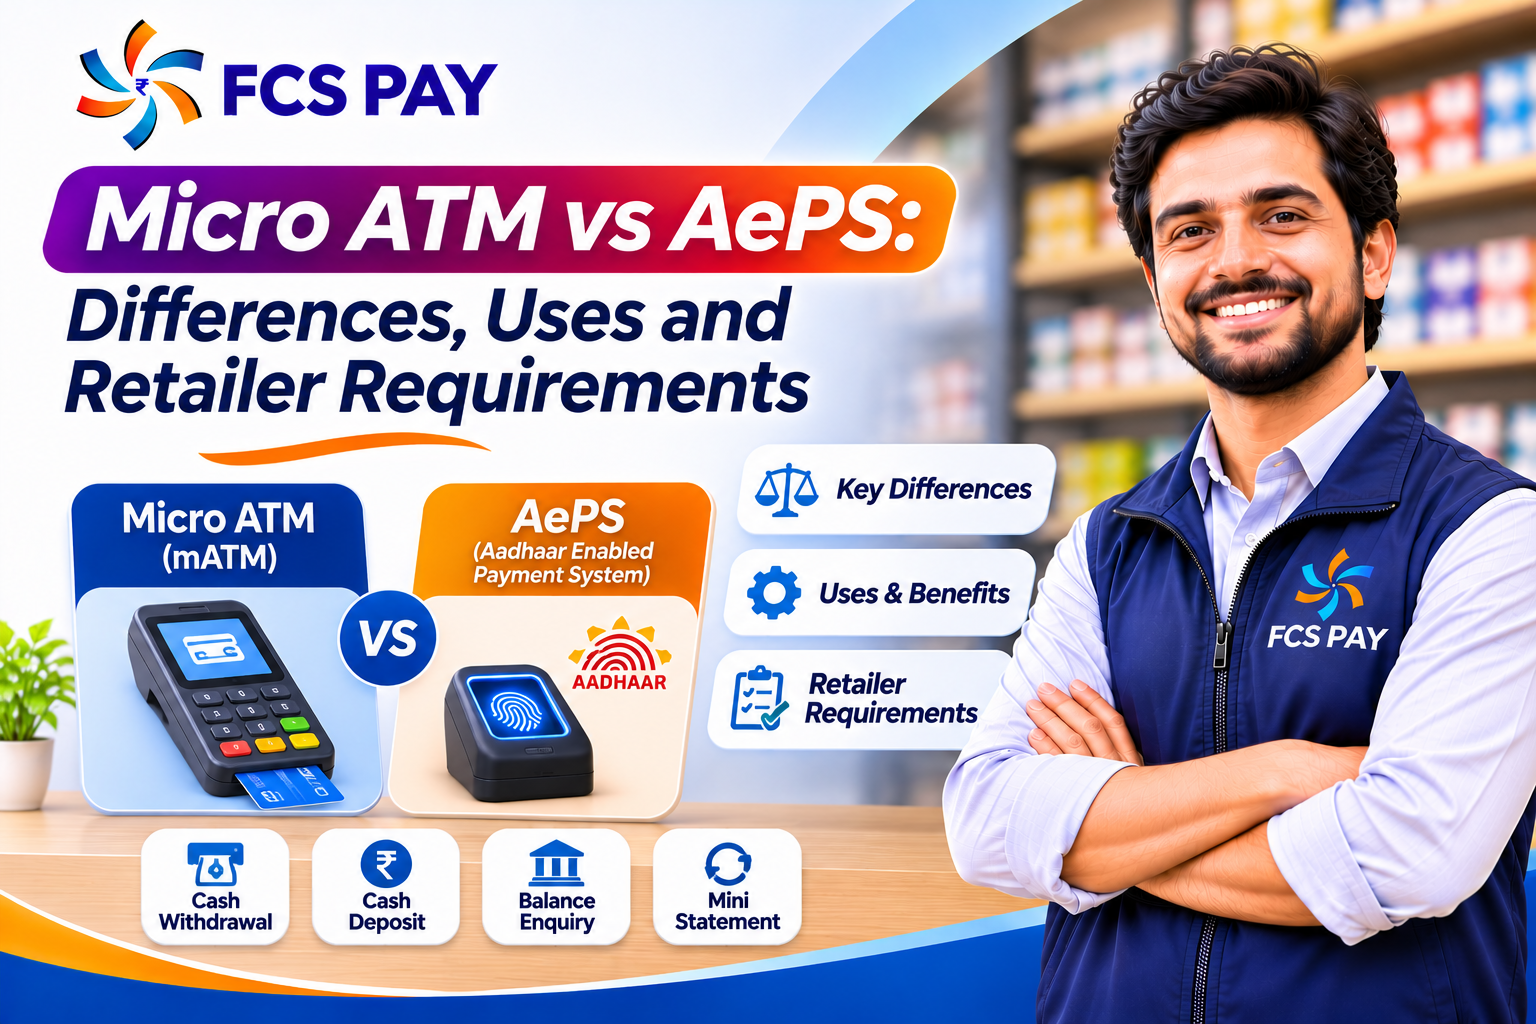
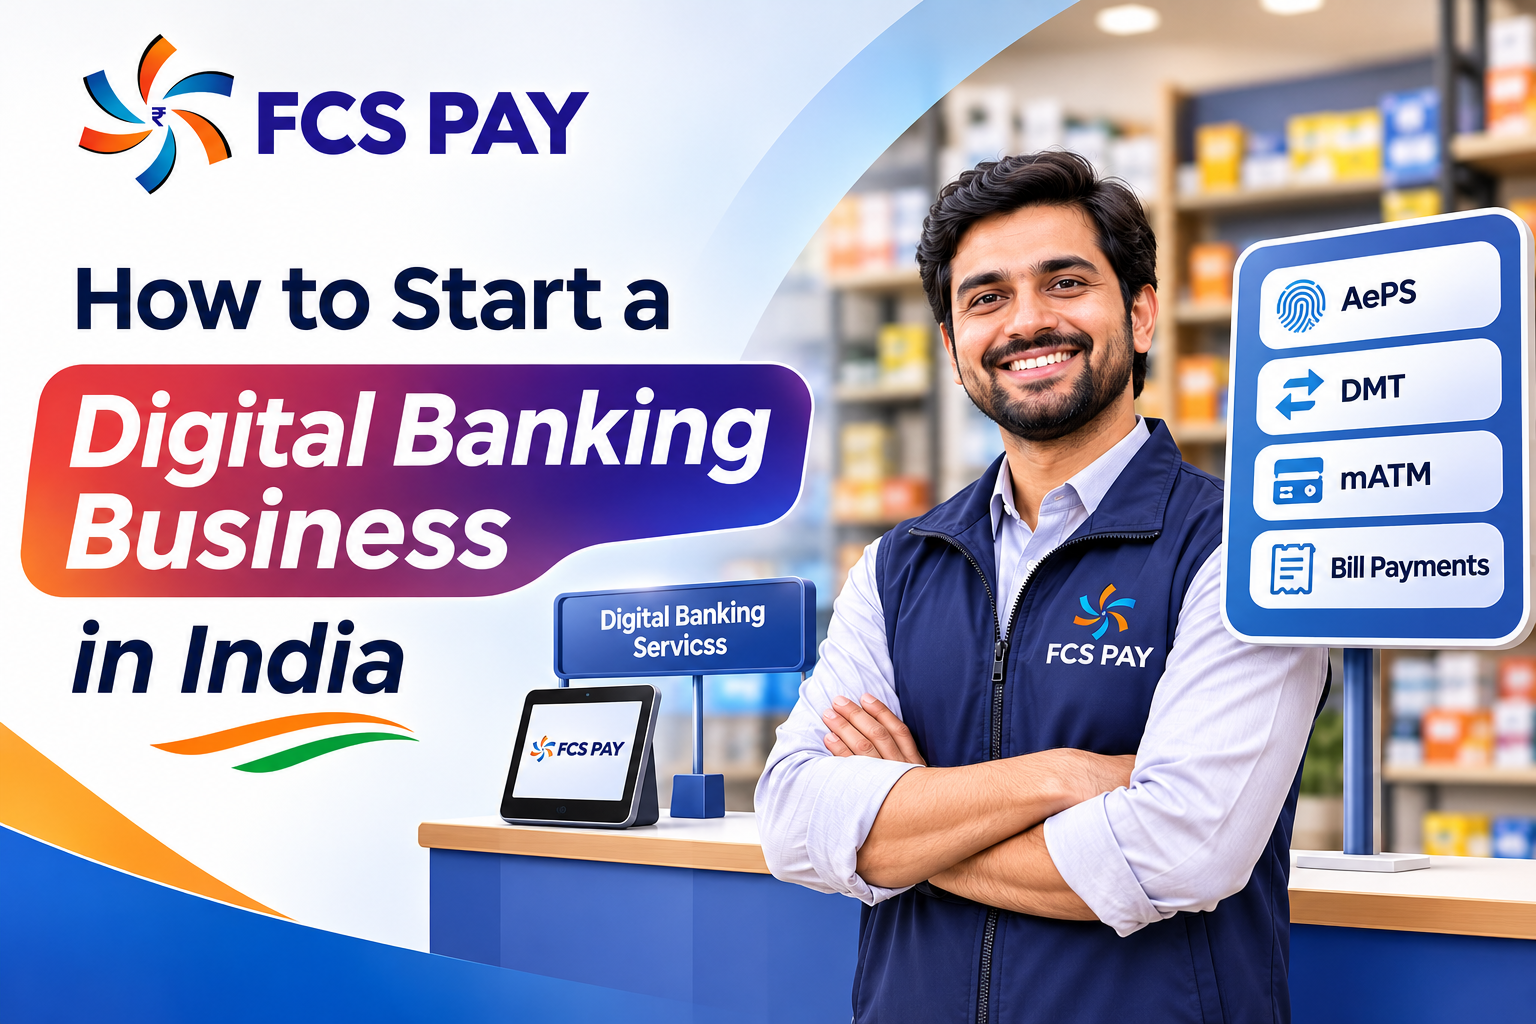
A digital banking services outlet helps customers access selected financial and payment services through an assisted retail channel. Depending on the provider, bank partnerships, device requirements and applicable regulations, services may include Aadhaar Enabled Payment System (AePS), domestic money transfer, Micro ATM transactions, mobile recharge and utility bill payments.
Service availability and eligibility differ by provider. Before offering any banking-related service, confirm the provider’s onboarding process, authorization requirements, transaction limits, fees and customer-verification procedures.
How to start a digital banking business in India
1. Assess your shop and local demand
Consider the customers who already visit your business and the services they commonly ask for. Shops in areas where customers value convenient access to assisted digital services may be well placed to assess this opportunity. Research nearby competition, customer footfall, connectivity and the time you can dedicate to service transactions.
2. Compare service providers carefully
Compare providers on service coverage, onboarding support, transaction success and reversal processes, customer support, settlement arrangements, device compatibility and transparent commercial terms. Ask for written details of commissions or fees rather than relying on verbal income promises. Confirm which entities actually provide or authorize each service.
3. Understand the documents and eligibility criteria
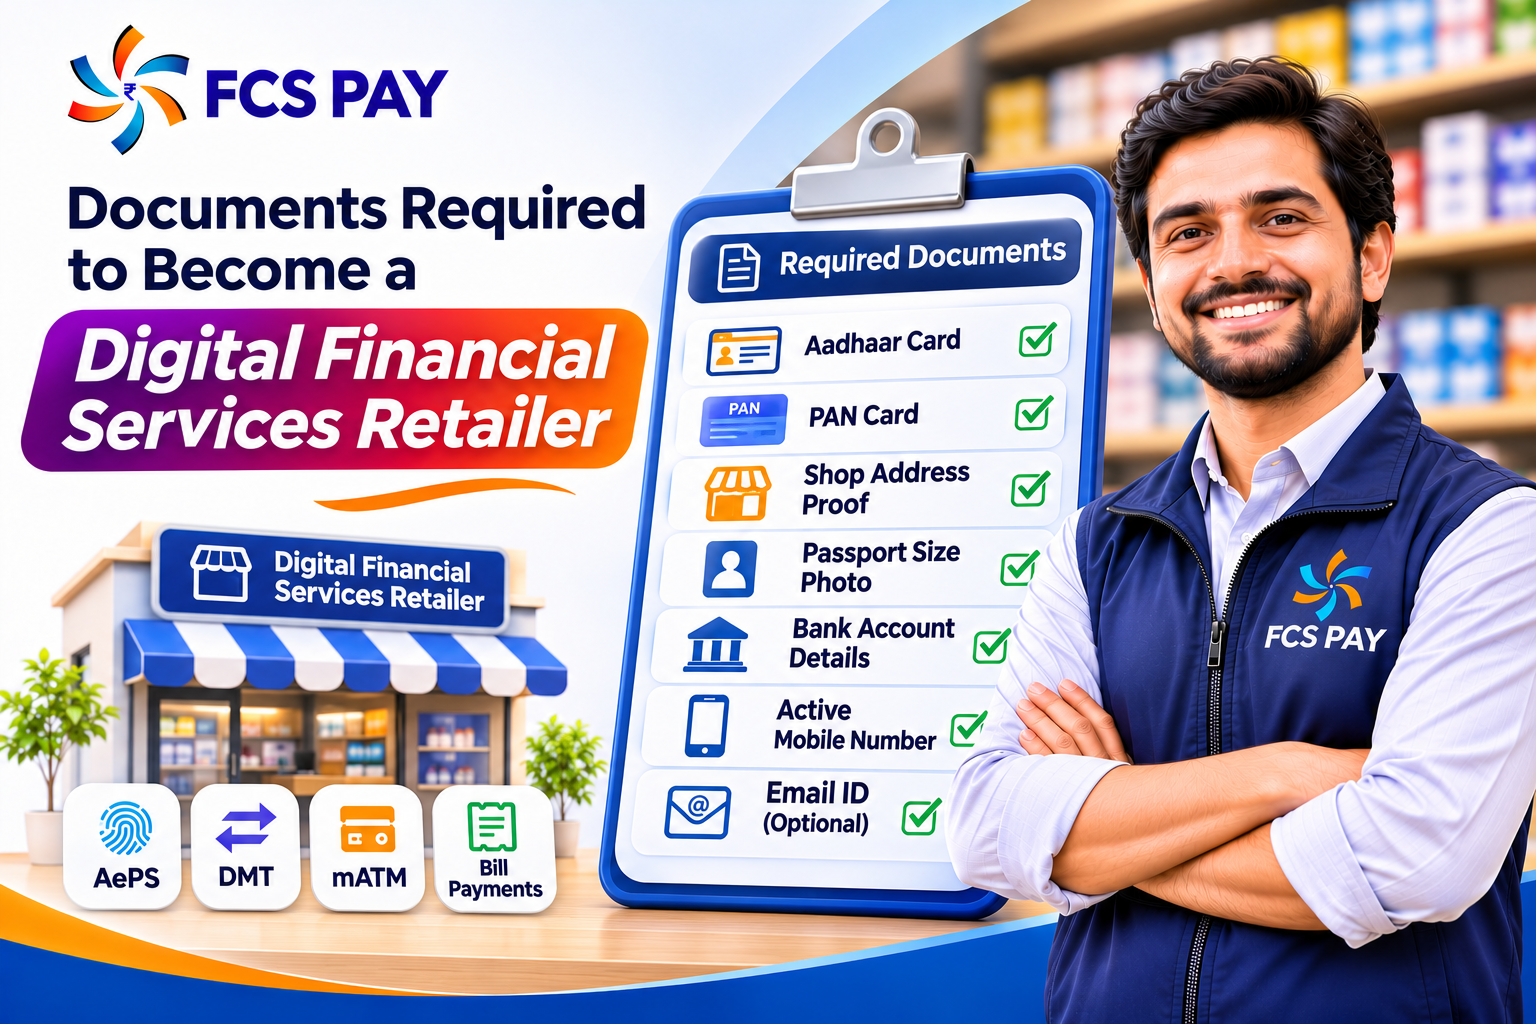
Provider requirements can vary. Be ready to ask about identity and address proof, PAN, bank-account details, shop or business information, photographs and any additional verification needed for the particular services you intend to offer. Submit documents only through the provider’s official, secure onboarding process and never share OTPs or biometric credentials with unauthorized persons.
4. Choose services that fit your customers
Learn what each service does before activating it. With an approved provider and eligible setup, AePS may enable supported Aadhaar-based transactions; domestic money transfer can support eligible transfers to bank accounts; and a compatible Micro ATM can support approved card-based banking transactions. Recharge and eligible bill-payment services may add further convenience.
Read more about FCSPAY AePS, Domestic Money Transfer, Micro ATM services and the available services. Check each service page and confirm current availability and eligibility before onboarding.
5. Prepare your shop and operating process
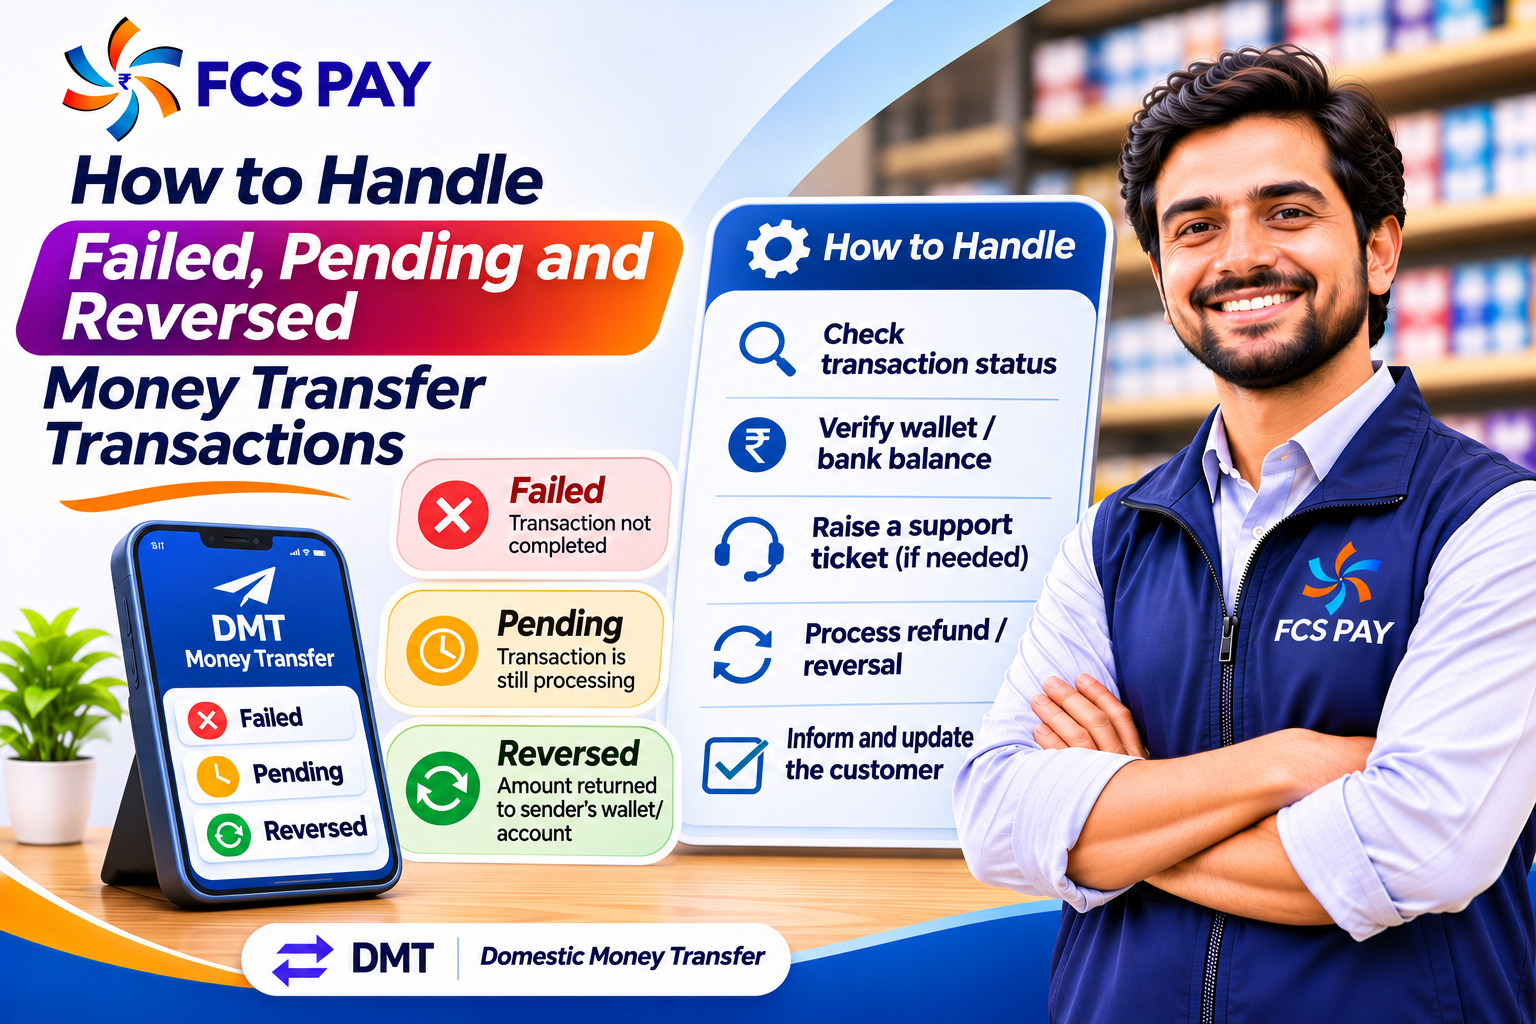
Arrange a reliable internet connection, a compatible device or approved biometric or card-reading equipment where required, and a safe way to manage transaction records. Keep customer information confidential, display applicable charges clearly and provide a receipt or transaction reference where available. Train staff to handle failed, pending and reversed transactions through the provider’s official support process.
6. Complete onboarding and test the workflow
Complete the provider’s verification and training requirements before serving customers. Understand the dashboard, transaction status messages, settlement timing and escalation channel. Do not advertise a service as active until you have confirmed that your account is approved and the service is enabled.
How much investment is required?
The investment depends on your existing shop, devices, connectivity, provider requirements and the services you choose. Prepare a simple budget that separates one-time costs from recurring costs. Ask whether any device deposit, activation fee, minimum balance or working capital is required, and request written terms before paying. Avoid providers promising guaranteed income or asking for unexplained upfront payments.
How can a retailer evaluate earning potential?
Earnings are not guaranteed. They depend on genuine customer demand, the services enabled, the provider’s published commission structure, successful transactions, operating costs and local competition. Estimate monthly results using conservative assumptions: expected transactions, actual commission per completed transaction, connectivity and device costs, staff time and any other charges. Verify all rates with the provider and do not base your decision on illustrative figures alone.
Why consider the FCSPAY retailer network?
FCSPAY provides a platform for retailers, agents and distributors to explore digital financial and business services. Prospective partners should review the current service list, onboarding criteria, support process and applicable terms to determine whether the network fits their business.
Learn more about becoming an FCSPAY retailer or explore the FCSPAY distributor program. Submit your details through the official website and confirm service eligibility, commercial terms and activation steps with the team.
Frequently asked questions
Can I start digital banking services from an existing retail shop?
Possibly. It depends on the provider’s eligibility criteria, location, required documents, equipment and approval process. Confirm the requirements for each service before investing.
Do I need a Micro ATM or biometric device?
It depends on the services you plan to offer. Some workflows require compatible, approved hardware, while other services may operate through a supported app or portal. Follow the provider’s current device and security requirements.
Is income from a digital banking outlet guaranteed?
No. Revenue depends on completed eligible transactions and the agreed commercial terms, while costs and demand vary. Ask for written commission details and calculate potential profitability conservatively.
Where can I learn about FCSPAY services?
Visit the FCSPAY services page and review the relevant service pages. Confirm current availability and onboarding requirements before offering any service to customers.
Ready to explore digital services for your shop?
Start by reviewing your local customers’ needs, comparing providers and understanding the operating requirements. If FCSPAY’s current services match your business goals, visit the Join FCSPAY page to explore the partner onboarding process.