Aadhaar Enabled Payment System (AePS) for Retailers in India
AePS services for retailers allow eligible customers to access supported banking services through an authorized service point using Aadhaar-based authentication. With FCSPAY, retailers, shopkeepers and agents can explore Aadhaar Enabled Payment System (AePS) services such as cash withdrawal, balance enquiry and mini statements, subject to service availability and applicable banking arrangements.
What Is Aadhaar Enabled Payment System (AePS)?
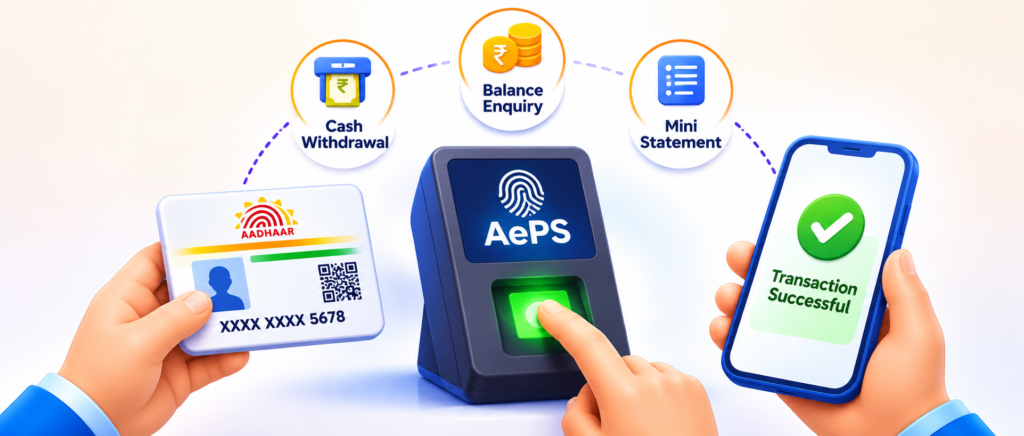
The Aadhaar Enabled Payment System (AePS) is a bank-led payment system that allows customers to access supported banking transactions using Aadhaar authentication through an authorized banking service point.
Customers can use their Aadhaar-linked bank account and the prescribed authentication process to request available banking services without using a debit card.
AePS is particularly useful for customers who prefer assisted banking services at nearby authorized retail outlets. It can help improve access to basic banking facilities in rural, semi-urban and urban communities.
The services available depend on the participating bank, authorized service provider, customer eligibility and activated platform.
AePS Services Available to Customers
Through an enabled AePS platform, eligible customers may access supported banking services. Common services include:
Customers can request cash withdrawals from their Aadhaar-linked bank accounts through an authorised AePS service point. The retailer follows the approved transaction process, and the customer completes the required biometric authentication. Cash should be handed over only after the transaction is confirmed successful.
Customers can check the available balance in their Aadhaar-linked bank account through a supported AePS transaction. This service allows customers to obtain account balance information at an authorised retail service point without visiting a bank branch.
A mini statement provides a limited record of recent account transactions, where supported by the participating bank and service platform. It helps customers review recent account activity and understand their latest transactions.
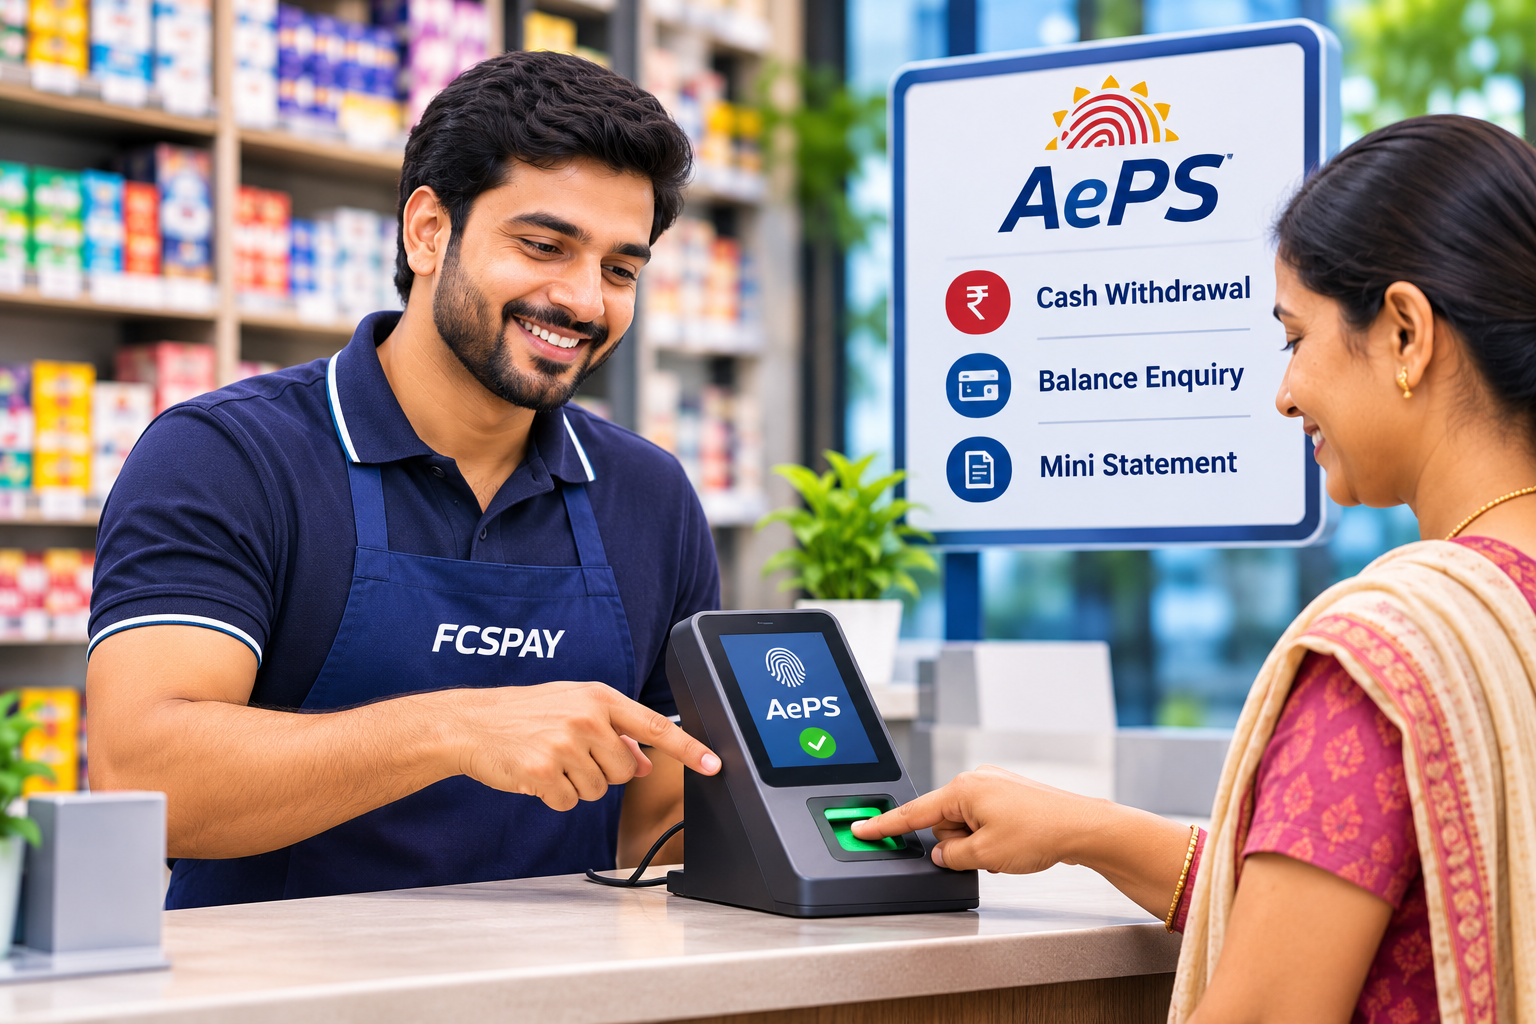
Note: The availability of individual AePS services may vary. Retailers should confirm the currently activated services, transaction limits and applicable terms before offering them to customers.
Benefits of Offering AePS Services Through a Retail Shop
Offering Aadhaar Enabled Payment System services can help eligible retailers expand their service offerings and meet everyday customer banking needs.
Retailers can offer supported Aadhaar-based banking services alongside their existing products and services, helping customers access basic banking facilities locally.
Customers may be able to access supported banking services at a nearby authorised retail outlet instead of travelling to another banking service point.
Eligible retailers can contribute to wider access to basic banking services by operating as authorized service points in their communities.
Adding AePS to your shop's services can help you serve more customer requirements and explore additional business opportunities. Any retailer commission depends on the applicable agreement and eligible transactions.
Why Explore AePS Services with FCSPAY?
FCSPAY is a digital financial services platform by STARTVIS TECHNOLOGIES PRIVATE LIMITED, helping retailers, merchants, agents and small businesses explore supported financial and business services.
Through FCSPAY, eligible retailers can enquire about Aadhaar Enabled Payment System services and understand the applicable onboarding and activation requirements.
Multiple Digital Services
Explore additional FCSPAY service categories, including:
- Domestic Money Transfer (DMT)
- Micro ATM services
- POS machine services
- Mobile recharge and utility bill payments
- PAN card services
- Insurance and travel services
Available transfer methods and processing times depend on the active service and receiving bank. Check the transaction status and reference details before attempting another transfer.
Domestic money transfers may use supported banking channels such as IMPS or NEFT, depending on the active service and provider arrangements. Check route availability before initiating a transaction.
Applicable transaction charges and retailer commission, if offered, depend on the current service provider agreement and commission schedule. Review the applicable terms before onboarding.
FCSPAY helps retailers explore domestic money transfer services and understand the required registration, KYC verification and activation process, subject to eligibility and provider approval.
Who Can Offer AePS Services?
Retail shops, merchants, small business owners and eligible agents may enquire about offering AePS services through an authorised provider.
The actual eligibility requirements depend on the provider, banking partner, retailer category and applicable verification process.
Businesses interested in AePS should check:
- Whether their business type is eligible.
- Which identity and business documents are required.
- Whether an approved biometric device is necessary.
- Which AePS transactions are enabled.
- What transaction limits and charges apply.
- How retailer commissions and settlements are handled.
- What support is available for pending or failed transactions.
FCSPAY helps interested retailers explore available digital financial service options. Onboarding and service activation are subject to eligibility, verification, partner approval and applicable terms.
Documents and Requirements for AePS Retailer Onboarding
The documents and equipment required for AePS onboarding may vary depending on the service provider and banking partner.
Retailers may be asked to provide:
- PAN card.
- Aadhaar or another accepted identity document.
- Business or shop details.
- Business address proof.
- Bank account information.
- Active mobile number and contact details.
- Additional KYC documents requested by the provider.
An approved biometric device, compatible application and reliable internet connection may also be required to facilitate AePS transactions.
Before purchasing any device, confirm the approved device specifications, compatibility and onboarding requirements with the provider.
Important Safety Practices for AePS Retailers
Customer privacy and transaction security are essential when providing Aadhaar-enabled banking services. Retailers should follow the authorized provider’s instructions and applicable operating requirements.
- Obtain the customer’s consent before initiating a transaction.
- Explain the transaction type and amount before submission.
- Use only approved biometric devices and authorized applications.
- Allow the customer to complete biometric authentication themselves.
- Never collect, store or share customer biometric information outside the authorized process.
- Do not disclose customer Aadhaar or banking information.
- Verify the final transaction status before handing over cash.
- Keep transaction references and receipts secure.
- Never repeat a pending transaction without checking its status.
- Report suspicious activity or device issues through authorized support channels.
Retailers should handle customer information responsibly and follow applicable Aadhaar, banking and data-protection requirements.
How to Handle Pending, Failed and Reversed Transactions
A transfer may sometimes show a pending, failed or reversed status because of a bank response, technical issue, connectivity problem or processing delay.
| Transaction Status | Meaning | What Should Retailers Do? |
|---|---|---|
| Pending Transaction | The final transaction status has not yet been confirmed. | Check the transaction status through the authorised platform and follow the provider’s instructions. Avoid submitting a duplicate transfer while the original transaction remains unresolved. |
| Failed Transaction | The transfer has been marked unsuccessful by the platform or banking service. | Check the failure reason and available transaction details. Follow the provider’s support process before attempting another transaction. |
| Reversed Transaction | The transferred amount has been returned through the applicable reversal process. | Confirm the reversal status through the authorised platform and communicate the available information to the customer. |
Important: For every unresolved transaction, keep the transaction reference number, date, amount and relevant status details available when contacting the service provider’s support team.
Frequently Asked Questions About AePS Services
What is AePS?
AePS stands for Aadhaar Enabled Payment System. It is a bank-led payment system that allows eligible customers to access supported banking services using Aadhaar-based authentication through an authorised service point.
What services are available through AePS?
Depending on the participating bank and enabled platform, services may include cash withdrawal, balance enquiry and mini statement.
Is a debit card required for AePS transactions?
No. AePS transactions use Aadhaar-based authentication rather than a debit card. The customer must have an eligible Aadhaar-linked bank account and complete the required authentication process.
Is biometric authentication required for AePS?
AePS transactions commonly use biometric authentication through an approved device. The exact authentication process must follow the authorized provider’s and applicable banking requirements.
Can a small retail shop offer AePS services?
Eligible retail shops and businesses may enquire about AePS onboarding through an authorized provider. Approval depends on business eligibility, KYC verification, equipment and partner requirements.
What documents are required for AePS retailer registration?
Requirements vary by provider. They may include PAN, identity proof, business details, address proof, bank account information and additional KYC documents.
Does an AePS retailer earn commission?
A retailer may receive commission under the applicable service agreement. Commission amounts, eligible transactions and payment terms depend on the provider’s current schedule and agreement.
What should I do if an AePS transaction fails?
Check the final transaction status through the authorised platform, retain the transaction reference and follow the provider’s support process. If the status is unclear, do not initiate a duplicate transaction until the original transaction is resolved.
What is the difference between AePS and Micro ATM?
AePS uses Aadhaar-based authentication, commonly through biometric verification, whereas Micro ATM transactions generally use a supported debit card and PIN. Both may support cash withdrawal and balance enquiry, subject to availability.
Is AePS available across India?
AePS operates through participating banks and authorised service points. Actual availability depends on the participating bank, provider, location, customer eligibility and active service arrangements.
Explore AePS Services with FCSPAY
Are you a retailer, shopkeeper or business owner interested in offering Aadhaar-enabled banking services?
Connect with FCSPAY to enquire about AePS service options, retailer eligibility, biometric device requirements and onboarding.
Join the FCSPAY network and explore digital financial services designed for your business.