Micro ATM services for retailers provide a way for eligible shops and service outlets to offer supported assisted banking transactions to customers. Through an enabled Micro ATM device and authorized banking network, customers may be able to withdraw cash, check their bank balance and request a mini statement using their debit card.
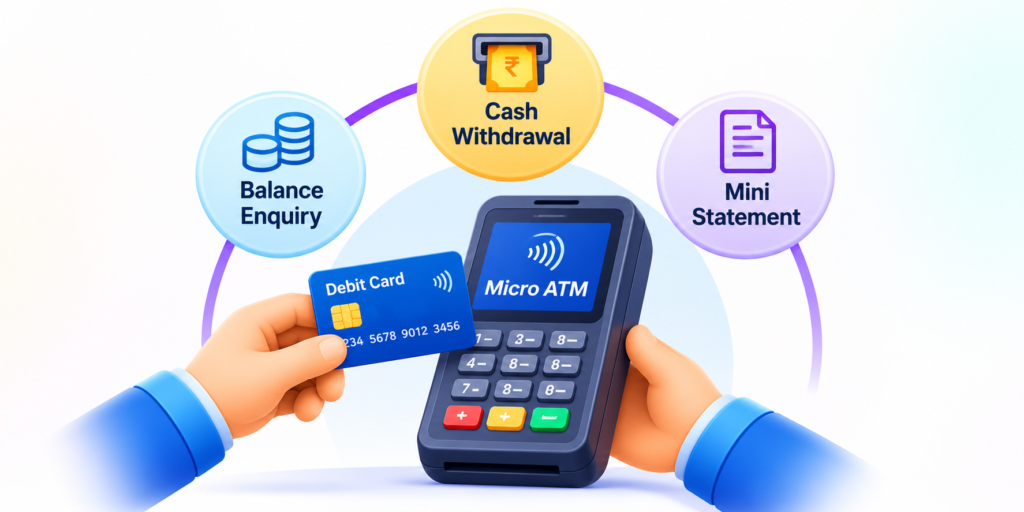
A Micro ATM is a compact electronic device used at an authorised retail or banking service point to facilitate supported banking transactions. It allows customers to access selected banking services without visiting a conventional bank branch or ATM.
For a typical debit-card Micro ATM transaction, the customer uses their own debit card and enters their PIN securely on the device. The transaction is routed through the authorised banking network, and its outcome depends on the issuing bank, service provider and network availability.
Micro ATM services can help extend access to basic banking facilities through eligible retail outlets, including in locations where conventional banking infrastructure may be less accessible.
The services available depend on the device, banking partner and activated platform. Commonly supported services may include:
Eligible customers can request cash withdrawals from their bank accounts using a supported debit card and PIN. The retailer processes the request through the authorised platform and provides cash only after the transaction is confirmed successful.
Customers can check the available balance in their bank account through a supported Micro ATM transaction. The displayed information depends on the response received from the banking network.
A mini statement allows customers to view a limited list of recent account transactions, where the service is supported by the issuing bank and transaction platform.
Always confirm the active service features before informing customers which transactions are available.
Micro ATM services can help eligible retailers expand the financial services available at their outlets.
Retailers can explore cash withdrawal, balance enquiry and mini statement services alongside their existing retail offerings, where supported.
Customers may be able to access supported banking services at a nearby authorised retail outlet, reducing the need to travel to another service point.
Offering useful services can give customers additional reasons to visit a retail outlet and may help build ongoing customer relationships.
Adding assisted banking services can help retailers serve additional customer requirements and diversify their service offerings. Actual earnings depend on the applicable commission agreement and transaction activity.
FCSPAY provides digital financial service options for retailers, agents and merchants. Eligible businesses can enquire about Micro ATM services and explore the applicable onboarding and activation requirements.
Retailers can also explore other service categories through FCSPAY, including:
Service availability depends on retailer eligibility, partner arrangements and activation status. Device supply, transaction limits, charges, commissions and settlement terms are governed by the applicable service agreements.
Available transfer methods and processing times depend on the active service and receiving bank. Check the transaction status and reference details before attempting another transfer.
Domestic money transfers may use supported banking channels such as IMPS or NEFT, depending on the active service and provider arrangements. Check route availability before initiating a transaction.
Applicable transaction charges and retailer commission, if offered, depend on the current service provider agreement and commission schedule. Review the applicable terms before onboarding.
FCSPAY helps retailers explore domestic money transfer services and understand the required registration, KYC verification and activation process, subject to eligibility and provider approval.
Retail shops, merchants and other eligible businesses may enquire about Micro ATM services. Actual eligibility depends on the service provider, banking partner, retailer category and applicable verification requirements.
Before applying, check:
FCSPAY helps interested retailers explore available service options. Onboarding, device allocation and activation are subject to eligibility, partner approval and applicable terms.
The documents required for Micro ATM onboarding may vary according to the provider and banking partner.
Retailers may be asked to provide:
A compatible device, supported application and required connectivity may also be necessary. Confirm the exact device specifications and onboarding process before purchasing any hardware.
Customer security is essential when providing assisted banking services. Retailers should follow the authorised provider’s operating instructions and maintain responsible transaction practices.
A Micro ATM transaction may sometimes remain pending or fail because of connectivity issues, banking network responses, card restrictions or other processing problems.
For a pending transaction, check the status through the authorised platform and follow the provider’s instructions. Avoid processing a duplicate withdrawal until the original transaction has been resolved.
For a failed transaction, review the response or error details and contact the provider’s support channel if required. If a customer’s account has been debited but cash was not received, record the transaction reference and follow the official complaint and resolution procedure.
Always communicate the confirmed transaction status to the customer.
A Micro ATM service allows customers to access supported banking transactions, such as cash withdrawals, balance enquiries and mini statements, through an authorized retail service point.
Depending on the active device and banking network, customers may be able to withdraw cash, check their account balance and request a mini statement.
No. Micro ATM card transactions use a supported debit card and PIN, whereas AePS uses Aadhaar-based authentication through an enabled service platform.
Eligible small retail shops may enquire about Micro ATM onboarding. Approval depends on the provider’s business, KYC, device and banking partner requirements.
Requirements vary, but may include PAN, identity proof, business details, address proof, bank information and additional KYC documents requested by the provider.
A retailer may receive commission under an applicable service agreement. The amount and payment terms depend on the provider’s current commission schedule and eligible transactions.
Check the transaction status through the authorised platform, retain the reference number and follow the provider’s support instructions. Do not initiate a duplicate transaction until the original status is clear.
Are you interested in offering assisted banking services from your retail shop? Contact FCSPAY to enquire about Micro ATM service options, retailer eligibility, device requirements and onboarding.
Explore FCSPAY services and enquire about becoming a retailer today.